
Newsletter Subscribe
Enter your email address below and subscribe to our newsletter
 ByJohn A
Brighton has long attracted people looking for a combination of coastal living, strong local amenities, employment opportunities and convenient connections to London. These characteristics can also make the city an area of interest for landlords considering buy-to-let property investment.
However, purchasing a property to let involves more than finding a home and collecting rent. Investors need to consider the local rental market, property type, financing, running costs, legal responsibilities and the needs of potential tenants.
Whether you are an experienced landlord or considering your first investment property, understanding the Brighton market can help you assess opportunities more realistically. Estate agents in Brighton can also provide local insight into rental demand, property values and the types of homes that may appeal to tenants.
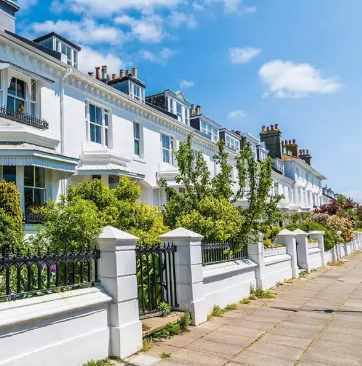
Brighton’s property market includes a wide variety of homes, from period terraces and converted flats to modern apartments and larger family properties. Different parts of the city can attract different types of tenants, so location should be considered alongside the property itself.
Tenant demand may come from professionals, students, families and people who want access to Brighton’s amenities while remaining within commuting distance of other parts of Sussex and London.
For landlords, this means identifying the likely target tenant before purchasing can be useful. A property suited to students may have different requirements from one intended for a professional couple or family.
See also: Artificial Intelligence in Packaging Design
The type of property you purchase can have a significant effect on its rental potential and ongoing costs.
A one-bedroom flat, for example, may appeal to a single professional or couple, while a larger house could be more suitable for families or sharers.
When assessing a property, consider:
It is important not to focus solely on purchase price or the number of bedrooms. A cheaper property may require significant improvements, while a slightly more expensive property in a location with strong rental demand could have different investment characteristics.
Understanding who rents in a particular area can help you assess whether a property is likely to attract suitable tenants.
Look at comparable properties currently available to rent and consider their asking rents, size, condition and location. You can also examine how quickly similar properties appear to leave the market, although advertised availability does not necessarily provide a complete picture of actual demand.
Speaking with local property professionals can provide additional context. Estate agents in Brighton may have insight into the types of properties tenants are currently asking for and the features that can influence rental interest.
However, rental demand can vary between neighbourhoods, so research should focus on the specific location rather than treating Brighton as one uniform market.
Rental yield is commonly used by landlords to assess the relationship between rental income and the property’s purchase price.
A basic gross rental yield can be calculated by dividing the annual rental income by the property’s purchase price and multiplying the result by 100.
For example, if a property costs £300,000 and generates £15,000 in annual rent, the gross rental yield would be 5%.
However, gross yield does not account for expenses. Landlords may need to consider mortgage interest, management fees, insurance, maintenance, service charges, ground rent where applicable, void periods and other property-related costs.
Looking at the potential net return can therefore provide a more realistic picture of the investment.
Buy-to-let mortgages work differently from standard residential mortgages, and the criteria can vary between lenders.
The amount you can borrow may depend on factors such as your deposit, expected rental income and personal financial circumstances. Interest rates and mortgage fees can also have a significant impact on the overall cost of borrowing.
Before purchasing an investment property, consider how changes in mortgage costs could affect your cash flow.
It is also important to understand the terms of the mortgage, including any restrictions on the property being rented out and potential early repayment charges.
Professional financial advice can help you understand the borrowing options available to you based on your individual circumstances.
The purchase price is only one part of the cost of owning a buy-to-let property.
Potential expenses can include:
You should also keep an emergency fund available for unexpected repairs or periods without rental income.
Creating a realistic cash-flow forecast before buying can help you understand whether the investment remains manageable when costs are higher than expected.
Landlords have legal responsibilities towards their tenants and must ensure that their properties meet applicable safety and regulatory requirements.
Depending on the property and tenancy, responsibilities can include gas and electrical safety, deposit protection, energy performance requirements and maintaining the property in a suitable condition.
Landlords should also keep up to date with changes to private renting legislation. Requirements can change over time, so relying on information from an old tenancy or previous investment may not be sufficient.
If you use a letting or property management service, establish which responsibilities will remain with you and which will be handled on your behalf.
Another important decision is whether to manage the property yourself or use professional support.
Self-management gives landlords direct control over tenant communication, maintenance and other aspects of the tenancy. However, it also requires time and an understanding of the relevant responsibilities.
A managed service may handle tasks such as finding tenants, arranging maintenance, collecting rent and managing tenancy administration.
The right approach depends on your available time, experience, location and willingness to handle day-to-day property issues.
A successful buy-to-let strategy should consider the people most likely to rent the property.
For example, a property close to transport links may appeal to commuters, while properties near educational institutions may attract students. Larger homes with gardens and several bedrooms may be more suitable for families.
Understanding your target tenant can influence decisions about property type, furnishings, layout, marketing and rental price.
The aim is not simply to maximise rent but to create a property that is appropriate for the local rental market and financially sustainable for the landlord.
Buy-to-let investment should not be treated as a decision that ends once a tenant moves in.
Landlords should periodically review rental income, operating costs, property condition and market demand. You may also need to consider whether improvements could make the property more attractive to tenants or improve its long-term performance.
Changes in mortgage costs, legislation, local demand and property values can all affect the investment over time.
Keeping accurate financial records can also make it easier to understand how the property is performing and identify areas where costs could be controlled.
Buy-to-let property investment in Brighton can involve a range of considerations, from choosing the right location and property type to calculating rental returns and understanding landlord responsibilities.
There is no single approach that works for every investor. Your strategy should reflect your budget, financing arrangements, investment objectives, risk tolerance and ability to manage the property.
Researching comparable properties, understanding local rental demand and calculating both income and expenses can help you make a more informed decision. Local estate agents in Brighton can also provide useful information about property values, rental demand and the characteristics of different areas.
Before committing to a purchase, consider the complete financial and practical picture rather than focusing on rental income or property prices alone. A well-researched approach can help you understand the potential opportunities and responsibilities involved in becoming a buy-to-let landlord.
